Why AML Matters in Insurance
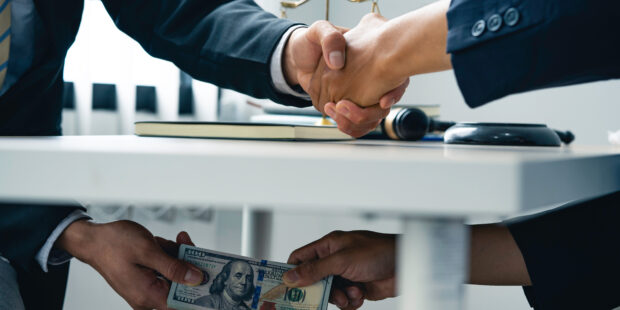
Insurance firms can be exposed to money laundering risks through policy purchases, claims activity, ownership transfers and other financial transactions. The complexity of insurance products and distribution structures can make it difficult to identify suspicious behaviour without robust oversight processes.
Criminals may attempt to use insurance products to:
- Conceal the origin of illicit funds
- Move money between entities
- Create apparently legitimate transactions
- Recover “clean” funds through cancellations or claims
Certain products and activities may present higher levels of risk, including:
- Single premium products
- Policy surrenders
- Ownership transfers
- Top-ups
- Arms-length onboarding
- High-risk jurisdictions
For insurers, brokers and MGAs, effective AML controls are essential not only for regulatory compliance, but also for protecting operational integrity and reputational trust.
On This Page
1. What is anti-money laundering?
2. Why AML matters in insurance
3. UK AML regulations explained
4. How money laundering works
5. AML risks in insurance
6. AML compliance requirements
7. FCA expectations and enforcement
8. AML technology and automation
9. AML resources and guidance
10. Frequently asked questions
2. Why AML matters in insurance
3. UK AML regulations explained
4. How money laundering works
5. AML risks in insurance
6. AML compliance requirements
7. FCA expectations and enforcement
8. AML technology and automation
9. AML resources and guidance
10. Frequently asked questions